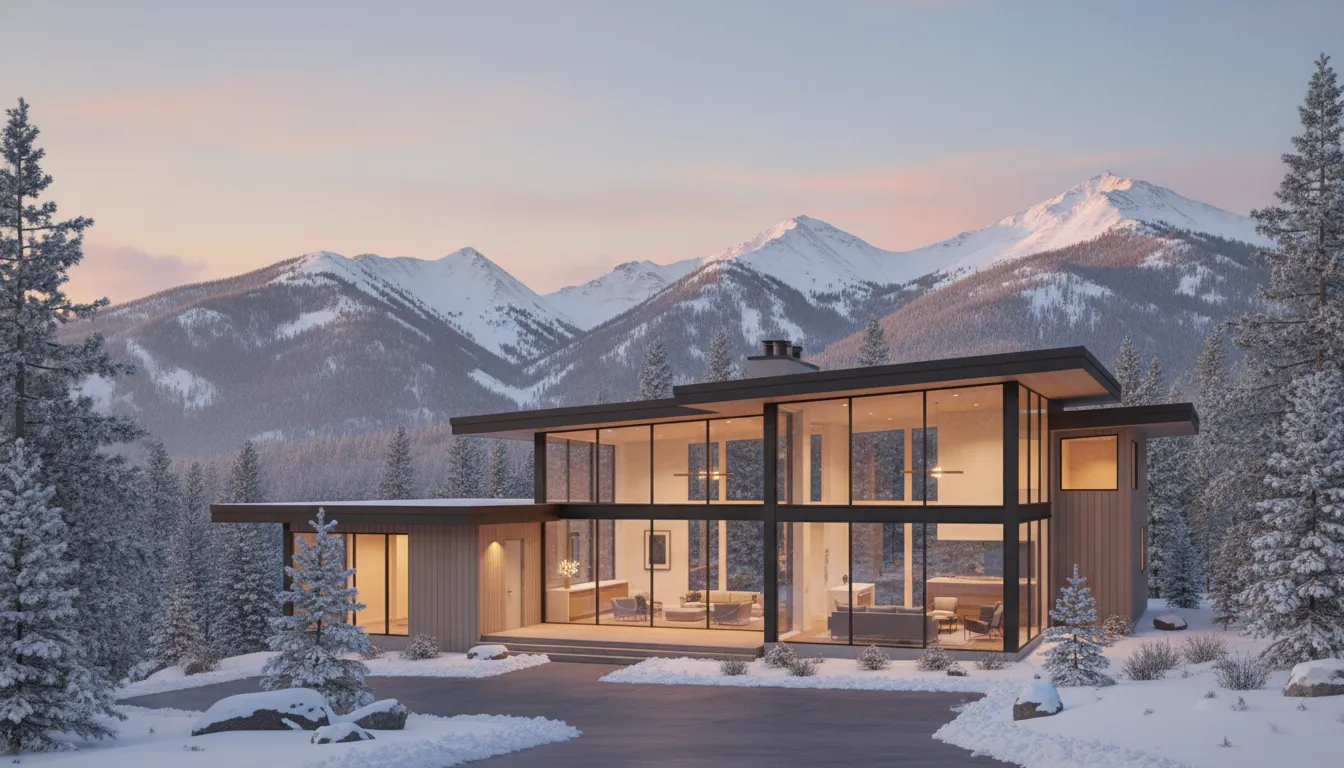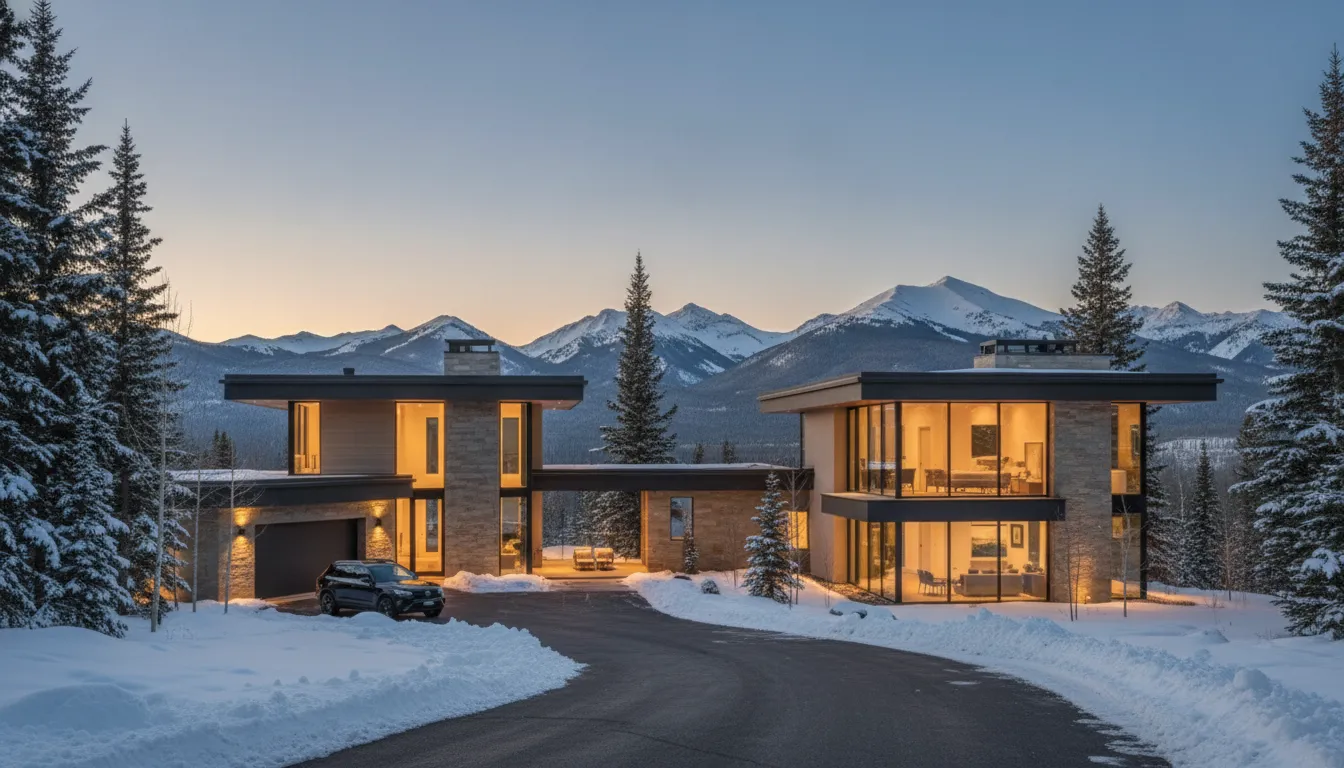

A ski-in/ski-out home in Park City can offer exceptional access, but the financing decision depends on more than the listing description. The property, intended use, loan size, documentation, and available liquidity all matter. Especially for a luxury residence in Deer Valley, Canyons Village, Empire Pass, The Colony, or another Summit County community.
Discuss your ski in ski out mortgage plans with Rodrigo Ballon
A ski in ski out mortgage may involve jumbo or second-home financing, but the right structure depends on the borrower's income. Assets, reserves, credit profile, and the property's verified access, type, appraisal, and HOA restrictions.
Before making an offer, it is worth treating ski access as a property due diligence question as well as a lifestyle benefit. A careful review can clarify what the collateral actually includes, how the home may be used, and which documents an underwriter will need. The first step is understanding what this financing can cover and where the property's ski designation fits into the loan analysis.
Direct answer: A ski in ski out mortgage finances the purchase or refinance of a qualifying property, not a special loan category created by the property's proximity to ski terrain. The financing may be structured as a jumbo loan, second-home loan, or another appropriate program, depending on the property's value, intended use, borrower profile, and applicable lender guidelines.
In Park City and Summit County, the phrase usually describes a residence where the owner can access maintained resort terrain from the property or a nearby designated route. Then return with little or no meaningful travel by car. It is not a regulated lending term, however. "Ski-in/ski-out" is a consumer phrase rather than a formal standard. So a listing description alone does not establish the property's access or its financing characteristics. A shuttle- or tram-dependent property may be resort-served without meeting a buyer's definition of true ski-in/ski-out access. Review a practical ski-access definition as part of your property due diligence.
The loan type follows the financial and property details, not the marketing label. If the requested loan exceeds the applicable conforming loan limit, it is generally considered a jumbo mortgage. The Consumer Financial Protection Bureau notes that jumbo mortgage costs may be higher than conforming mortgage costs, although actual terms depend on the complete application and lender guidelines. Summit County conforming limits can change annually, so avoid treating a fixed dollar threshold as permanent. A Park City buyer can review Park City jumbo loan options in that broader context.
Many ski residences are acquired as second homes, while others may be primary residences or investment properties. Intended occupancy matters because each use can carry different documentation, reserve, property, and underwriting considerations. A luxury condo in Deer Valley, a residence in Canyons Village. And a home in a community such as Empire Pass or The Colony may also present different HOA documents, access arrangements, and property characteristics for review.
For borrowers with substantial assets, equity compensation, business income, or multiple income sources, the central question is not simply whether the home is ski-in/ski-out. It is whether the property and the borrower's documented financial profile support a suitable financing structure. Loan size, income, assets, credit, reserves, debt-to-income ratio, occupancy plans, and lender requirements all contribute to that assessment. Confirming the actual ski route and assembling the property file early can help create a clearer conversation before you commit to a financing strategy.
Direct answer: Treat "ski-in/ski-out" as a marketing description, not a regulated property standard. Before you commit, verify the actual route, elevation, legal access, maintenance responsibilities, and everyday convenience through maps, records, site inspection, and HOA documents. A resort or HOA shuttle may provide useful access, but it is generally resort-served rather than true ski-in/ski-out access.
This diligence matters in Park City, Deer Valley, Canyons Village, Empire Pass, The Colony, and other Summit County communities. Two nearby residences can have materially different routes, appraisal considerations, HOA rules, and financing eligibility.
For a ski in ski out mortgage, the access label is only one part of the evaluation. Confirm the property facts before you structure financing, particularly when the home is a luxury condo, second home, or investment property with additional HOA and occupancy considerations.
Review the ski-access terminology and due-diligence framework.
Direct answer: A Park City ski property may be financed with a fixed-rate jumbo, an adjustable-rate jumbo, second-home financing, or an alternative-documentation program, depending on the borrower and the property. The right structure depends on intended use, income profile, assets, reserves, loan size, property type, lender guidelines, and market conditions.
Many resort purchases fall above applicable conforming loan limits and are therefore generally considered jumbo mortgages. Summit County limits can change annually, so the classification should be confirmed for the specific transaction. A ski-in/ski-out designation does not create a separate mortgage category, and a listing description does not determine whether a lender will accept the property as collateral.
| Approach | May fit when | Key questions to review |
|---|---|---|
| Fixed-rate jumbo | You value payment predictability over the planned ownership period. | Does the loan size, property type, liquidity, credit, income, and reserve profile meet applicable jumbo guidelines? |
| Adjustable-rate jumbo | You have a defined ownership, sale, or refinance strategy and understand the adjustment features. | How could future adjustments affect the plan, and is the strategy realistic if timing or market conditions change? |
| Second-home financing | The residence is intended for personal use as a second home and meets occupancy requirements. | How will personal use, location, property type, and any rental plans be documented and evaluated? |
| Bank-statement or other alternative documentation | You are self-employed or have complex income that conventional documentation may not fully represent. | Can 12 to 24 months of personal or business statements, CPA confirmation, a profit-and-loss statement, and entity documents support the application? |
For many Park City jumbo purchases, down payment expectations are commonly discussed in a range of 10% to 20%, but that is not a universal requirement. A higher-value property, complex income, unusual ownership structure, or specific lender policy may call for a different contribution or additional reserves. Program availability and documentation requirements also vary.
If the property will be used as a second home, review the distinctions carefully in Park City second home loans. Before selecting a structure, discuss the property's exact location, access, HOA or condominium documents, intended occupancy, liquidity goals, and income documentation with a qualified mortgage professional. That property-specific review is especially important for buyers using business income, equity compensation, or multiple entities.
Direct answer: A lender evaluates both your financial profile and the ski property's quality as collateral. For a Park City purchase, that commonly means reviewing credit patterns, documented income and assets, debt-to-income ratio. Cash reserves, appraisal support, property type, HOA documents, intended occupancy, and the details behind the resort access being represented.
Credit review is broader than looking for one isolated late payment. HUD guidance describes past credit performance as a useful guide to future payment behavior and directs underwriters to examine the overall pattern of credit conduct. A period of financial difficulty does not necessarily make a borrower unacceptable when a good payment record has been maintained for a considerable period afterward. If your profile includes a business transition, liquidity event, or other unusual history. Prepare a clear explanation and supporting documentation rather than assuming the file will speak for itself. HUD credit guidance provides additional context.
Income and assets receive similarly detailed attention. An underwriter may need to verify salary, bonuses, equity compensation, self-employment income, business distributions, investment accounts, and the source of funds for closing. The analysis can be more involved for executives, entrepreneurs, 1099 earners, and borrowers with multiple entities. Debt-to-income ratio is considered alongside loan size and the strength of the overall file. Cash reserves may also matter, particularly when the property is a high-value second home, has seasonal ownership considerations, or carries substantial HOA obligations. Requirements depend on the borrower, property, lender, and program.
The property itself must support the requested financing. An appraisal is a written opinion of value, and it may explain the features contributing to value and compare the home with nearby properties. The Consumer Financial Protection Bureau notes that a lender may require a new appraisal for a purchase or refinance. In a resort market, the appraiser may need to analyze limited or highly specialized comparable sales, property type, location, condition, views, access, and seasonal market characteristics. See the CFPB appraisal guidance for the basic role of an appraisal.
Finally, underwriting may examine HOA declarations, bylaws, rental restrictions, maintenance responsibilities, parking, insurance, and any easements affecting access. Intended occupancy matters as well. A primary residence, second home, and investment property can be evaluated under different guidelines, and a listing's ski-in/ski-out label does not establish financing eligibility. Reviewing the resort collateral and HOA file early can reveal questions before the loan reaches final review.
Direct answer: Prepare a complete, organized picture of your income, assets, debts, reserves, intended use, and the specific Park City property before underwriting begins. The right documentation depends on how you earn income, how your assets are held, the loan size. And the property's type and restrictions, so early transparency is more useful than assembling a generic checklist.
Start with current identification, authorization for credit review, recent income documentation, and records supporting your available funds. A W-2 borrower may need conventional employment and pay records. A self-employed or 1099 borrower should be ready to discuss business ownership, distributions, tax returns, and whether business cash flow is distinct from personal liquidity. Depending on the program and profile, bank-statement underwriting may use 12 to 24 months of personal or business statements. Along with CPA confirmation, a profit-and-loss statement, and entity documents.
Executives should identify how stock options, RSUs, bonuses, or other variable compensation are earned, vested, and documented. Borrowers using trusts, partnerships, LLCs, or multiple entities should gather formation documents, ownership records, trust documents, and statements that clarify access to funds. These documents do not establish eligibility by themselves, but they help the lender evaluate documented income and assets without overlooking relevant context.
Keep the purchase contract or listing information, legal description, unit details, and intended occupancy together. State whether the home is planned as a primary residence, second home, or investment property. That distinction can affect the review, and rental plans should be described accurately rather than assumed to qualify.
For a Park City condo or resort residence, request available HOA documents early. CC&Rs, bylaws, budgets, insurance information, rental rules, parking provisions, snow-removal responsibilities, and access or easement language can all matter. A ski-in/ski-out label does not prove identical access, value, appraisal treatment, or financing eligibility. A lender with local resort-market experience can help identify appraisal, HOA, and collateral questions before they become late-stage surprises.
For a more detailed documentation roadmap, review Park City jumbo pre-approval. Then agree on a communication plan: disclose changes in employment, debts, asset transfers, ownership structure, or intended use promptly, and ask before moving funds between accounts. Jumbo underwriting commonly considers credit, documented income and assets, debt-to-income ratio, and cash reserves. Requirements vary by loan size, property type, and lender, so preparation improves clarity but cannot guarantee approval or particular terms.
Direct answer: Financing a resort property in Deer Valley or Summit County is not based on the listing label alone. A lender must review the property's actual access, physical characteristics, ownership structure, HOA rules, intended use, and the borrower's complete financial profile. Local market knowledge helps identify the right questions early, but every home is still reviewed individually.
That distinction matters across Deer Valley, including Empire Pass, as well as Canyons Village, The Colony, Old Town, Promontory, and other Summit County resort areas. A condo near a lift, a townhome with a defined trail connection, and a single-family home marketed as ski-accessible may have different collateral and documentation considerations. The relevant question is not simply whether a listing says "ski-in/ski-out." It is how the property connects to maintained terrain. Whether that route is available, and what rights or obligations govern access.
Access can affect how a buyer evaluates the property, but it does not replace an appraisal or underwriting review. Resort properties may present appraisal challenges when comparable sales differ in elevation, trail proximity, views, unit configuration, or private amenities. An appraisal is an opinion of value that may explain a property's features and compare it with nearby properties. And a lender may require one for a purchase or refinance. See this resort property financing overview for additional context.
HOA and community documents also deserve close attention. Depending on the property, governing documents may address easements, snow removal, parking, exterior ski storage, guest access, rentals, and maintenance responsibilities. These details can be especially important in planned resort communities such as The Colony or Empire Pass. Promontory and other private communities may introduce their own property, membership, or use considerations. Old Town properties can differ again because location, building type, access arrangements, and shared ownership structures may vary from one property to the next.
A local specialist can help organize those questions alongside the standard review of credit, documented income, assets, reserves, debt-to-income ratio, loan size, and intended occupancy. That perspective may be particularly useful for buyers using a home as a second residence. Evaluating rental use, preserving liquidity, or documenting income from a business, equity compensation, or multiple entities. It does not guarantee eligibility or a particular loan structure. Program availability and requirements depend on the borrower, property, market conditions, and lender guidelines.
Talk with Rodrigo Ballon about a ski in ski out mortgage for your Summit County property
A ski-in/ski-out property offers practical, direct access between the home and a lift, trail, or skiable route. The phrase is used loosely, so verify the actual route, snow conditions, elevation, building orientation, and year-round access rather than relying on listing language alone.
Possibly. A loan above the applicable conforming limit is generally considered jumbo, and Summit County limits can change annually. The appropriate structure depends on the purchase price, intended occupancy, property type, financial profile, and lender guidelines.
Prepare documentation for income, assets, liabilities, credit, reserves, and intended use of the property. Business owners and other self-employed borrowers may also need personal or business bank statements, a profit-and-loss statement, CPA confirmation, and entity documents, depending on the program.
Usually not. A home that depends on a resort or HOA shuttle, tram, or other transportation may be resort-served rather than truly ski-in/ski-out. Confirm the route on official maps and through the HOA, and review easements, maintenance obligations, storage rules, and access restrictions before you commit.
Start early, keep financial documentation organized, avoid unexplained account changes, and clarify whether the home will be a primary residence, second home, or investment property. Provide the property details and HOA materials as soon as they are available so appraisal and collateral questions can be addressed early.
A ski-in/ski-out purchase deserves a financing conversation that considers both the property and the borrower. Rodrigo Ballon can help you organize the questions that matter for a Park City or Summit County home. Including intended use, access, HOA documentation, appraisal considerations, income structure, assets, reserves, and the loan programs that may fit your goals.
Discuss your ski in ski out mortgage options with Rodrigo Ballon
Utah's Home Lender operates under CrossCountry Mortgage, LLC, NMLS #3029. Equal Housing Lender. Rates, loan limits, down payments, reserves, documentation, terms, and program availability vary by borrower, property, market conditions, and lender guidelines. This information is for educational purposes and is not a commitment to lend or a guarantee of approval, rates, terms, or results.