


If you are researching a vacation home mortgage The Colony Utah buyers can use, start with the property's intended use and the complete financial picture. The Colony at White Pine Canyon is a distinctive Park City setting, and a purchase there may involve a second-home classification, jumbo financing, detailed property review, and a borrower profile that does not fit a simple W-2 template.
Talk to a vacation home mortgage specialist about The Colony.
Financing a vacation home in The Colony usually begins with three questions: Will the home be used primarily as a second home, does the loan amount require jumbo financing, and can the borrower document income, assets, reserves, and occupancy plans? The answers shape the available structure, documentation, property review, and consultation path.
This checklist is designed for high-income and high-net-worth buyers considering a mountain residence for personal use. It does not publish live rates or promise approval. Rates, terms, down payments, reserves, documentation, and program availability vary by borrower, property, market conditions, and lender guidelines.
A The Colony purchase is not evaluated only by the home's location or purchase price. The lender also needs to understand how the residence will be occupied, how the loan fits the buyer's assets and income, and whether the property supports the proposed financing structure.
The Colony at White Pine Canyon is marketed as a private, on-mountain Park City community with direct access to a high-end mountain lifestyle. The official community site provides local context about its setting and homes. That context matters because resort properties can have distinctive construction, access, insurance, appraisal, and association considerations.
For a buyer, the phrase "vacation home" describes the lifestyle goal. In mortgage underwriting, the more important question is often whether the home qualifies as a second home under the applicable program guidelines. That classification is separate from the buyer's broader wealth and does not automatically follow from calling a property a retreat, chalet, or vacation residence.
Utah's Home Lender approaches the conversation around the specific property and the borrower's broader strategy. A buyer may be moving between primary-residence obligations, business ownership, investment assets, stock compensation, or seasonal use. A focused review can identify which facts need documentation before a purchase contract creates unnecessary timing pressure.
Local knowledge is useful, but it does not replace underwriting. The right next step is a property-specific discussion that considers intended occupancy, financing amount, property characteristics, income, assets, and liquidity goals together.
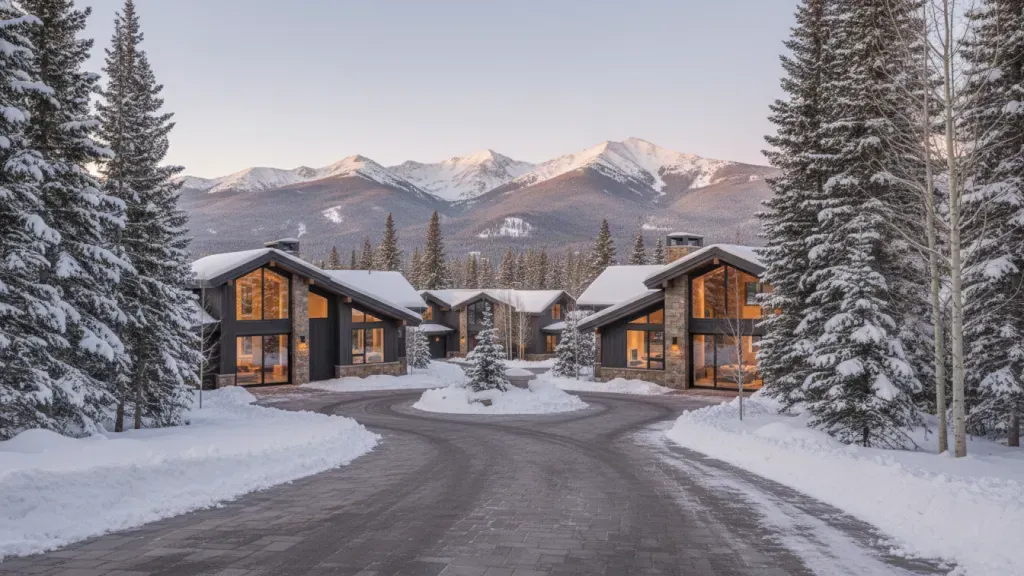
The occupancy classification depends on how the borrower will use and control the home. A personal-use second home is not the same as an investment property purchased primarily to generate rental income, even when both are located in a resort market.
Fannie Mae's occupancy guidance describes second-home requirements that include borrower occupancy for part of the year, a one-unit dwelling suitable for year-round occupancy, exclusive borrower control, and no arrangement that makes the property a rental or timeshare. Program and lender rules can differ, so the applicable guideline set must be confirmed for the actual transaction.
That distinction should be settled early. A buyer who expects personal use but may also rent the home occasionally should explain the plan accurately. A buyer who is purchasing primarily for rental income may need an investment-property structure instead. Misstating occupancy can create avoidable underwriting problems and may affect the documentation, pricing, reserves, and loan options considered.
| Question | Second-home direction | Investment-property direction |
|---|---|---|
| Primary purpose | Personal enjoyment and occasional use | Ownership primarily connected to rental income |
| Occupancy | Borrower uses the home for part of the year | Borrower may not occupy the property as the main use |
| Income treatment | Rental income may not be used automatically to qualify | Rental income and operating assumptions may be central to review |
| Planning priority | Document personal use, assets, and reserves | Document property income, expenses, and investment structure |
The table is a planning tool, not a determination of eligibility. If your plans combine personal use, seasonal rental activity, and long-term investment goals, raise that combination before submitting a loan application. Utah's Home Lender can help organize the question for a property-specific review without assuming the answer.
For a broader explanation of the distinction, see the related guide to what counts as a second home in Park City. The The Colony article should stay focused on local preparation and financing decisions rather than repeating that full definitional guide.
Prepare a clear occupancy explanation, income records, asset and reserve documentation, information about existing obligations, and the property's contract and community materials. The goal is to give the lender a complete picture before the property and loan structure are finalized.
A strong initial file is organized around the borrower and the property. Requirements vary, but a high-value second-home conversation commonly addresses the following:
Self-employed and high-net-worth borrowers may benefit from discussing documentation strategy before the file is assembled. The strongest path is not always the one with the fewest documents. It is the one that presents income, assets, liquidity, and obligations in a way that is complete, consistent, and appropriate for the chosen program.
Many luxury mountain purchases require a loan amount above the applicable conforming limit, making jumbo financing part of the conversation. The exact structure depends on the county, unit type, loan amount, down payment, borrower profile, property eligibility, and lender guidelines.
The Federal Housing Finance Agency explains that loans above the applicable conforming loan limit are known as jumbo loans. Because limits can change and may vary by county and property type, avoid building a purchase plan around an old threshold. Confirm the current limit for the specific transaction.
In The Colony, the property review deserves attention alongside the loan amount. A lender may need to understand the home's construction, access, appraisal support, insurance, utilities, association or community documents, and any features that make the residence different from a standard suburban property. This does not mean a distinctive home is automatically ineligible. It means the questions should be surfaced early.
A buyer may also compare fixed-rate and adjustable-rate jumbo structures. That comparison should reflect the intended holding period, liquidity plan, tolerance for payment changes, and broader wealth strategy. Utah's Home Lender does not publish a current rate promise in this guide because pricing and terms are transaction-specific.
For a broader Utah financing framework, review the Utah jumbo loan guide and the customer service page for jumbo loan options. Those resources provide wider context, while this page remains focused on The Colony vacation-home preparation.
Qualification is based on more than annual income. A lender may evaluate recurring income, assets, debt obligations, down payment, reserves, credit, and the relationship between the proposed home and the borrower's broader financial plan.
A vacation home can sit within a complex financial picture. One borrower may own a company, another may receive stock compensation, and another may be selling an existing property while purchasing in Park City. Each situation calls for documentation that explains both the source of funds and the expected continuity of the financial profile.
Liquidity is especially important to discuss when a buyer wants to preserve capital for business operations, investments, renovations, or future opportunities. A larger down payment can change the amount financed, but it can also change the buyer's post-closing liquidity. There is no universal down-payment answer that applies to every The Colony purchase.
Consider a hypothetical buyer who lives outside Utah, owns a technology company, and wants a personal-use mountain home while keeping business reserves intact. That buyer may need to explain business income, available assets, existing housing obligations, and intended occupancy together. The example is illustrative, not a promise that any particular profile will qualify.
Reserves should be considered in the context of all housing obligations, not just the proposed payment. A buyer may need to account for insurance, taxes, maintenance, association costs, travel, seasonal operations, and the obligations attached to a primary residence. The lender will determine which items count and how they are documented under the applicable program.
If your income is irregular, begin early. Bank statements, business records, tax returns, award documentation, or other records may be relevant depending on the program and borrower. Do not assume that a high asset balance eliminates the need to explain income, debt, or recurring obligations.
Utah's Home Lender can discuss how a fixed-rate jumbo loan, adjustable-rate jumbo loan, or another available structure may fit the stated plan. Any option remains subject to complete underwriting, property review, and lender guidelines.
Ask whether the property supports the intended occupancy, whether its documents are available for review, how its construction and access may affect appraisal or insurance, and whether the expected loan amount aligns with the property and borrower profile.
Before an offer or application, ask the real estate and lending teams to coordinate on the questions that can affect financing:
The answer to each question may change the sequence of the transaction. For example, property details may need review before a buyer commits to a structure, while a complex income profile may require an earlier documentation conversation. A local lender can coordinate the checklist, but the final decision remains subject to the applicable lender's review.
Buyers comparing resort locations can also review the related Canyons Village vacation-home guide and Deer Valley vacation-home guide. Those articles cover neighboring resort contexts. They are not substitutes for a The Colony property review.
The next step is a property-specific consultation, followed by a review of occupancy, documentation, loan size, assets, reserves, and property materials. Bring the purchase timeline and explain the intended use plainly so the financing conversation starts with accurate facts.
Use this short checklist before reaching out:
Request a property-specific vacation home mortgage consultation for The Colony.
A second-home mortgage may be available when the property and intended use meet applicable program and lender requirements. Confirm occupancy and eligibility before applying.
No. A vacation home is generally evaluated for personal use, while an investment-property loan is tied primarily to rental or investment use. Classification depends on the facts.
It may, if the proposed loan exceeds the conforming limit for the property's county and unit type. Confirm the current limit and structure for the transaction.
A self-employed buyer may need income, business, tax, asset, and reserve documentation. The exact list depends on the program and the complete borrower profile.
Rental plans can affect occupancy classification and qualification. Disclose the intended use and confirm whether any rental income may be considered under the applicable guidelines.
The best financing conversation starts with accurate occupancy plans, complete documentation, and a clear view of the property's unique characteristics. A local consultation can help you identify the next questions without promising a specific approval, rate, or term.
Utah's Home Lender, led by Rodrigo Ballon at CrossCountry Mortgage, helps high-income buyers evaluate financing for luxury residences, second homes, and other high-value properties in Park City and Summit County. The review can include income structure, assets, reserves, property details, and the intended use of a The Colony home.
Discuss your The Colony second-home mortgage options with Utah's Home Lender.
Rates, terms, down payments, reserves, documentation, and program availability vary by borrower, property, market conditions, and lender guidelines. CrossCountry Mortgage, LLC, NMLS #3029. Licensed by the Utah Department of Financial Institutions. Equal Housing Lender. Rates, terms, and availability are subject to change without notice. Not a commitment to lend.




