

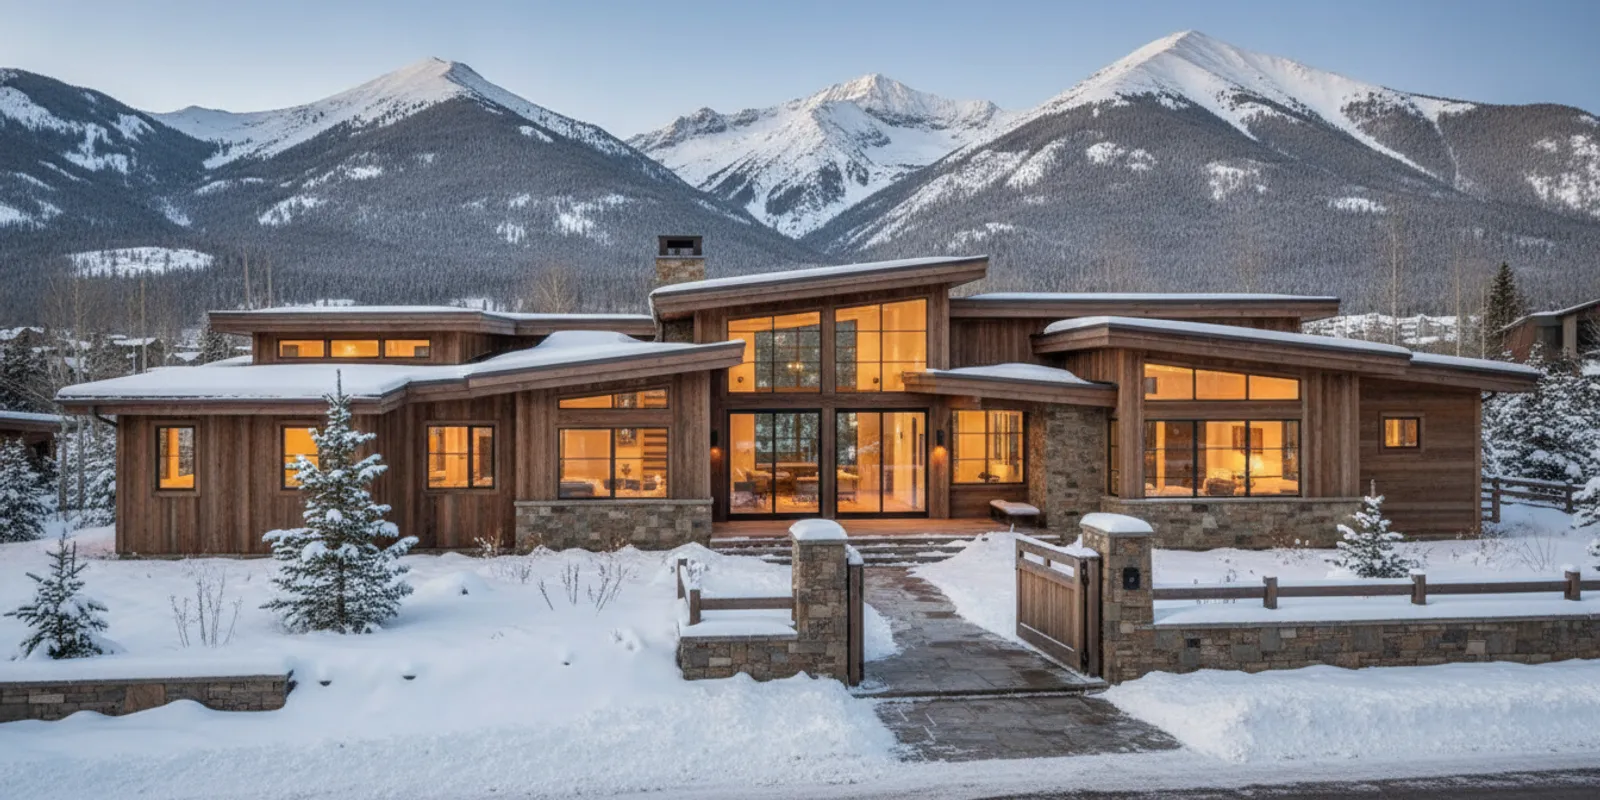
A second home mortgage in The Colony, Utah, should be built around the property and how you plan to use it. A luxury home in this Park City community can call for a closer look at occupancy, finances, reserves, and the property itself than a routine primary-home purchase. Clarifying those details early can help you compare financing options before you write an offer.
Talk with Rodrigo about a second home mortgage in The Colony
The right financing conversation starts with the specific home, not only its price. The Colony is a luxury community in the Park City area, and property type, intended occupancy, and your overall financial profile can all affect the available path.
Second-home financing is not interchangeable with financing for a primary residence or an investment property. A lender will want to understand how the home will be used. A property you intend to occupy personally as a retreat may be reviewed differently from a home primarily operated as a rental. Describe your actual plans clearly and ask how they affect the program options being considered.
Also distinguish the purchase from your broader balance sheet. Buyers may have income from a business, stock compensation, investments, or more than one property. The goal is to present a complete and consistent picture, rather than assume that a high asset level alone answers every underwriting question.
For a broader overview of financing in the area, review the information about jumbo loans in Utah and the guide to jumbo loans in Park City. Those resources can help frame a discussion, but the right structure depends on the property and borrower.
Occupancy is one of the first facts to define. Tell your mortgage professional whether the home will be a personal second residence, an investment property, or a property with mixed use, and be specific about any rental plans.
Second-home and investment-property financing can involve different eligibility standards, documentation, down-payment expectations, and reserve requirements. Exact terms depend on lender guidelines, the property, market conditions, and your individual profile. Do not select an occupancy category based on which one seems more favorable. The application and supporting information need to reflect your genuine plans.
For example, imagine a business owner considering a ski home for personal use during planned visits, while also weighing whether to rent it occasionally. Before relying on rental income or assuming a particular loan classification, the buyer should explain the intended use and ask what documentation is needed. The lender can then discuss which options may fit the facts. This is an illustration, not a statement that a particular program or approval is available.
Property use is also relevant if the home is a condominium or condo hotel. Those property types can have their own project, association, and occupancy considerations. If you are evaluating that kind of purchase, see the overview of condotel financing in Park City and the guide to getting a loan for a condo hotel.

A clear financial picture makes it easier to have a useful conversation about structure. Gather information about income, assets, liabilities, other real estate obligations, and the funds you expect to use for the purchase.
Borrowers with straightforward salary income may have familiar pay and tax documents to provide. A self-employed buyer or business owner may need to explain income that does not appear as a simple salary. A 1099 earner may have variable earnings. A technology executive may receive salary, bonuses, restricted stock, or other compensation on different schedules. Each profile is assessed under the applicable program guidelines, so documentation needs can vary.
Consider organizing the following before you request a property-specific review:
This is a planning list, not a universal underwriting checklist. A lender may request different documents based on your circumstances and the financing path. If standard tax-return income does not tell the whole story, ask whether alternative documentation or a non-QM option could be considered. Learn more about non-QM home loans and the jumbo loan process for self-employed borrowers.
Compare the full cash commitment, not just the amount due at closing. Down payment, closing costs, and post-closing reserves can all matter to your plan, while preserving liquidity may be important if you own a business or several properties.
There is no single down payment figure that applies to every Colony purchase. Requirements can vary with loan size, occupancy, property characteristics, credit profile, assets, and lender guidelines. A conversation should compare realistic structures based on your financial priorities, rather than promise a particular threshold.
Some buyers prefer a larger down payment to reduce the amount borrowed. Others want to keep more capital available for investments, business needs, or property improvements. A larger loan may also bring different qualification considerations. Ask for a side-by-side review that describes the cash needed, expected monthly obligations, reserve expectations, and how each approach affects your remaining liquidity. Do not treat an illustrative estimate as a loan offer or guaranteed terms.
| Planning factor | What to clarify | Why it matters |
|---|---|---|
| Intended use | Personal second home, investment use, or another arrangement | Occupancy affects which financing options may be considered. |
| Down payment | Funds available and the amount you want to commit | Changes the requested loan amount and remaining liquidity. |
| Reserves | Assets you can retain after closing | Other properties, obligations, and program guidelines may shape reserve review. |
| Income profile | Salary, business income, 1099 income, or equity compensation | Documentation and qualifying-income analysis differ by borrower. |
| Property details | Home type, condition, association, and any rental plan | Property characteristics can affect eligibility and lender review. |
Buyers comparing a larger loan amount can also review jumbo loan down-payment considerations. The article is general information; use a current, property-specific review to understand how the details apply to your purchase.
When comparing written mortgage offers, read the terms and costs side by side and ask about any item you do not understand. The Consumer Financial Protection Bureau provides consumer information about financial products, including mortgages, that can help frame questions during the shopping process. Use the specific disclosures and current documents for your transaction when evaluating an offer.
Review the home and its ownership structure early, and share relevant details with your lender. A financing discussion is more useful when it accounts for the actual property rather than a general description of a luxury home.
Gather the listing information, purchase timeline, property type, and any available details about a homeowners association or shared amenities. If the home is part of a condominium project, ask whether project review or association materials may be needed. If it is a single-family home, disclose any features or planned use that could affect the lender's assessment. The exact review depends on the loan and property.
Think through practical ownership costs as well. A second home may involve maintenance, insurance, association dues, utilities, travel, and seasonal upkeep. These expenses are separate from the mortgage payment but can affect whether the overall purchase fits your plans. Buyers should evaluate ongoing costs using current information from appropriate providers, not rely on a broad estimate.
If rental use is part of your plan, make that clear at the start. Discuss how the use may affect the application and whether projected rent can be considered under a particular program. Do not assume anticipated rental income will be counted or that short-term rental activity is permitted by the association or local rules. Verify applicable requirements for the specific property.
Bring the key facts together and ask for a comparison that reflects your priorities. A productive discussion should connect property use, documentation, cash strategy, and timing without implying that approval or specific terms are certain.
For a second residence, a fixed-rate jumbo mortgage and an adjustable-rate mortgage may be among the structures to discuss, depending on availability and fit. An adjustable rate can change according to its terms after any initial period, so ask how adjustments work and whether the payment could fit your longer-term plan. Compare the full terms and risks, not only an initial payment estimate. A consultation can also consider whether alternative documentation is relevant to a complex income profile.
To prepare for the broader process, you may find it useful to read about steps for getting a mortgage for a second home and factors to understand when reviewing second-home financing costs. No article can determine eligibility for a specific transaction.
Ask questions that reveal both the assumptions and the practical tradeoffs. Clear answers help you understand what is known, what still needs review, and which details could change the analysis.
Rodrigo Ballon works with borrowers through CrossCountry Mortgage, LLC, NMLS #3029, and focuses on financing conversations for Park City and Summit County properties. Share the purchase details and financial context openly so the discussion can be tailored to the facts. Loan programs, rates, terms, down payments, reserves, documentation, and availability vary by borrower, property, lender guidelines, and market conditions. A discussion is not a commitment to lend or a guarantee of approval.
Discuss your second home mortgage plans with Rodrigo
That depends on the actual occupancy plan and applicable program guidelines. Explain any planned rental use before applying, and ask how it may affect the loan classification and documentation. Do not represent an investment property as a personal second home.
Not automatically. The loan amount and applicable conforming limits, along with property and borrower details, determine whether a particular loan is considered jumbo. Limits and program rules can change, so confirm current details for the transaction.
Self-employed borrowers may have financing options, but income documentation and analysis depend on the program and the complete financial profile. Be ready to explain how the business operates and provide the records requested. Eligibility is not guaranteed.
There is no universal answer. Compare how long you expect to own the home, the full payment terms, potential future adjustments, your liquidity goals, and your tolerance for payment changes. Ask for a review based on current options and your circumstances.
Bring basic information about the property, intended use, income sources, assets, liabilities, and expected funds for the purchase. The mortgage professional can identify which supporting documents are appropriate for a more detailed review.
Share the property, your intended use, and your financial profile to discuss a second home mortgage structure that may fit your plans. Talk with Rodrigo about a second home mortgage
With an early, property-specific review, you can understand which details need attention and make a more informed financing decision before moving forward.




